Medical costs in India have been skyrocketing over the past few years. They’re rising by around 14% every year (the fastest rate in Asia). The majority of healthcare is paid for out of pocket, and lending to pay off your medical bills makes up roughly 23% of your total hospital bill, which puts an enormous amount of financial strain on families. This growing trend indicates that having the proper health coverage is no longer about preference but rather a necessity.
The difference between mediclaim and health insurance can be challenging for many people to grasp. Mediclaims only cover hospitalization (hospital stays and in-hospital procedures), while medical insurance may offer more extensive coverage for additional costs, like treatment for a critical illness, day-care procedures, and much more. Knowing the main distinctions will help you determine the right coverage based on your individual needs and finances.
What is Mediclaim?
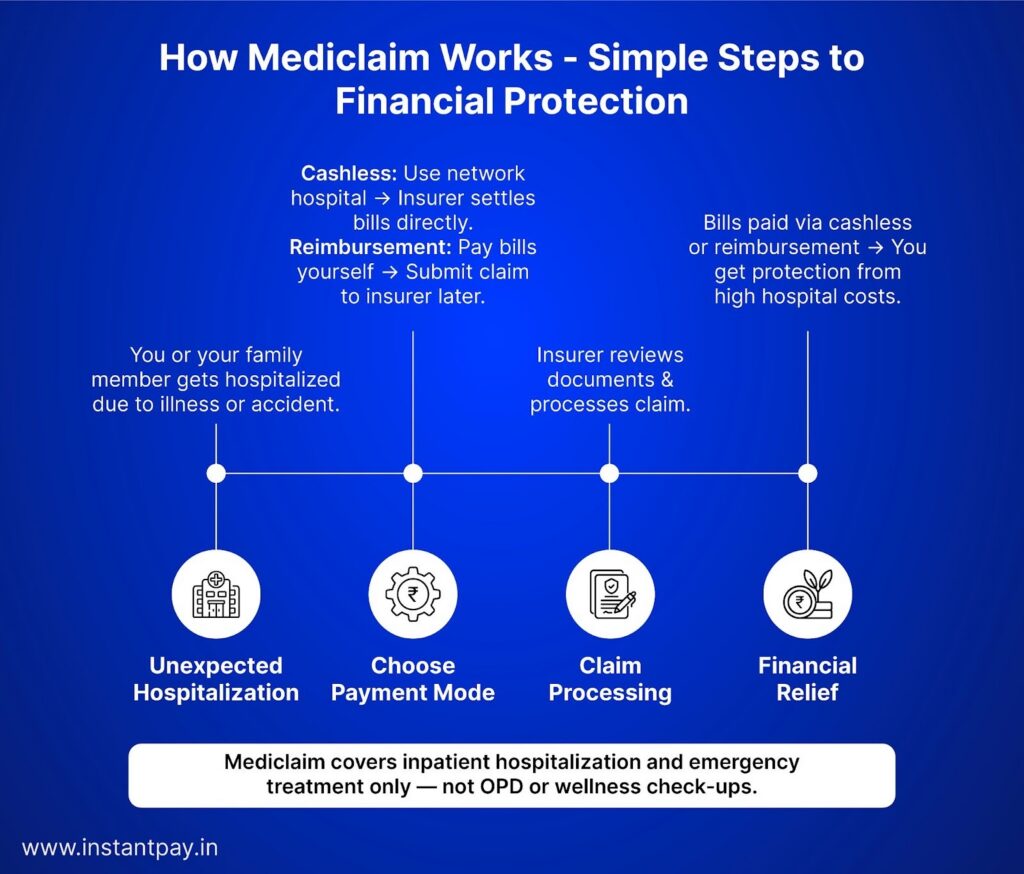
Medical coverage is a primary source of medical coverage that assists in paying for hospital expenses incurred from an accident or illness. You can pay the hospital bills directly or use the cashless option at participating hospitals, with the insurance company paying the hospital yourself.
A medical plan primarily covers treatment and emergency hospital services and typically will not cover routine doctor visits or preventative care. A medical plan is a viable option for those looking for essential medical coverage at an affordable rate.
Key Features & Benefits of Mediclaim
- Covers hospitalization: Covers the cost of a hospital bed, doctor’s fees, nursing care, surgery, and tests during hospital stay.
- Accident and Illness Coverage: Medical coverage for hospital care due to an accident or illness.
- Sum Insured is limited: Medical coverage typically provides coverage for a maximum amount of Rs.500,000.
- Cashless and Reimbursement Options: You can either get cashless treatment at a hospital or get reimbursed for treatment at a hospital.
- Tax benefit: The premiums paid for medical coverage qualify for deductions under section 80D of the Income Tax Act.
- Affordable premium: Because it primarily covers inpatient hospital expenses, the cost of a medical coverage plan is generally lower than a full-coverage policy.
- Family floater options: Multiple family members can be insured under a single policy, which shares the total amount covered (sum insured).
What Does Mediclaim Not Cover?
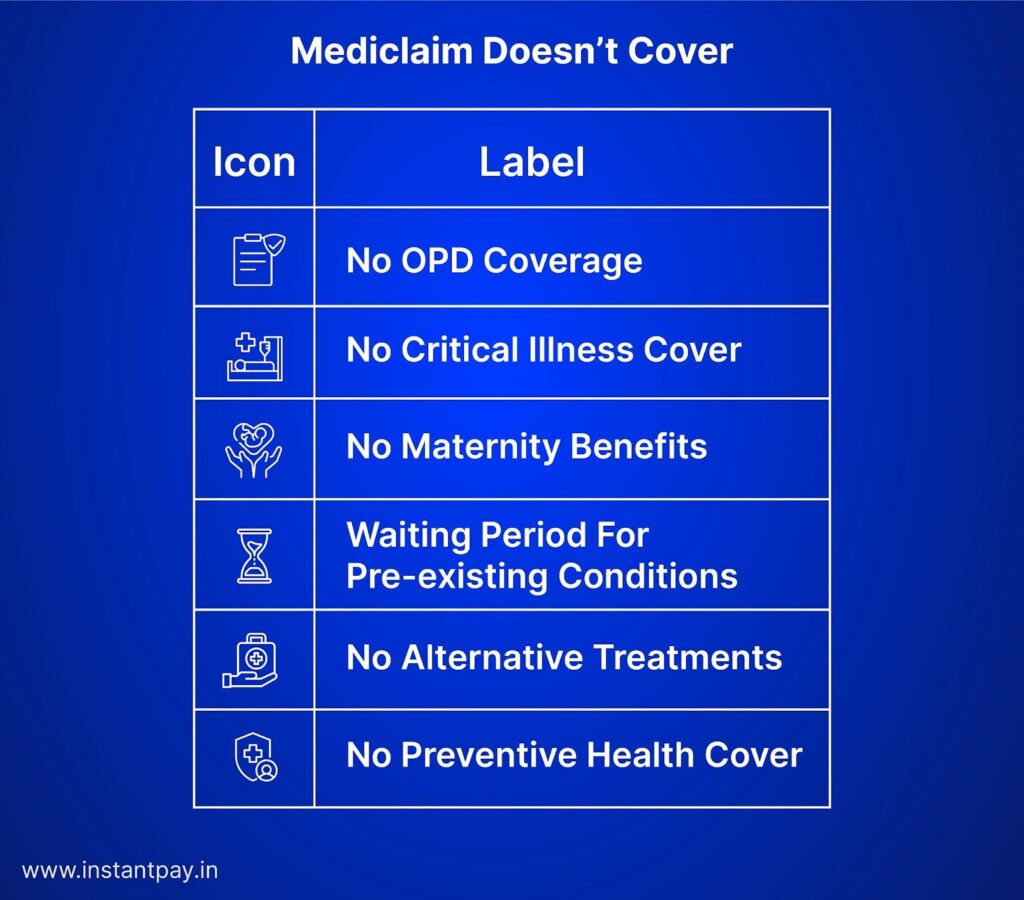
Pre and post hospitalization expenses is a collection of insurance policies that provide coverage for hospitalization in India but generally include many limitations. As mediclaim policies only cover inpatient treatment, where the patient will spend at least one night in hospital, many common day-to-day medical expenses and also many specialized treatments are excluded.
Typical exclusions on many mediclaim policies are:
- No OPD Coverage: A doctor’s consultation, medication, and diagnostic testing are usually covered only if the patient has been directly admitted to the hospital.
- No Critical Illness Coverage: A number of major illnesses, including cancer, and organ failure, will usually not be covered unless they require hospitalization during the period of cover of the Pre and post hospitalization expenses policy.
- No Maternity Benefits: Generally excluded are all expenses related to pregnancy, childbirth, and the care and treatment of newborn babies.
- Pre-existing conditions that are covered under a mediclaim policy usually have a waiting period of between 2 and 4 years before you will be eligible for any Pre and post hospitalization coverage.
- No Preventive or Wellness Cover: Things such as routine health checks, vaccinations, and wellness programs (coaching, fitness programs & gym memberships) will not be covered by a mediclaim policy.
What is health insurance?
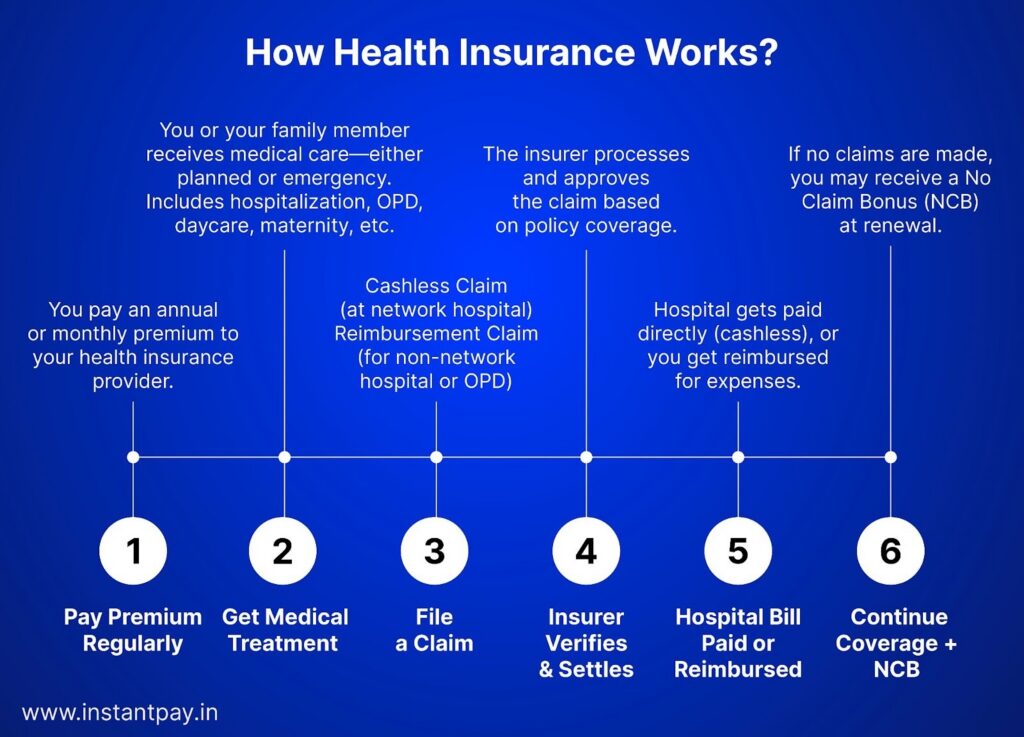
Health insurance is an extensive, well-rounded plan to assist you in covering the expenses associated with many medical expenses, not just hospital stays. A plan’s benefits may include daycare treatment, the pre- and post-hospitalization treatment, coverage of critical illness, preventative health check-ups, and in some cases even maternity or OPD (outpatient department) expenses.
You pay a consistent amount (called a premium) on a monthly basis to your insurer. The insurer pays (or reimburses) you for the expenses you incur for treatment for an illness or an injury. By using health coverage, you can spend less on out-of-pocket healthcare expenses and be assured that you can access the necessary treatment without feeling financially stressed.
The broadened protection that health plan provides is driving rapid adoption. India’s health insurance market was valued at USD 97.51 billion in 2024 and is forecast to reach USD 315.84 billion by 2034, or a compounded annual growth rate (CAGR) of 12.47%.
| Mediclaim = Covers only hospitalization |
| Health Insurance = Broader coverage including outpatient, critical illness, and add-ons Ideal for: Individuals or families looking for holistic healthcare protection over time |
Key Features and Benefits of Health Insurance
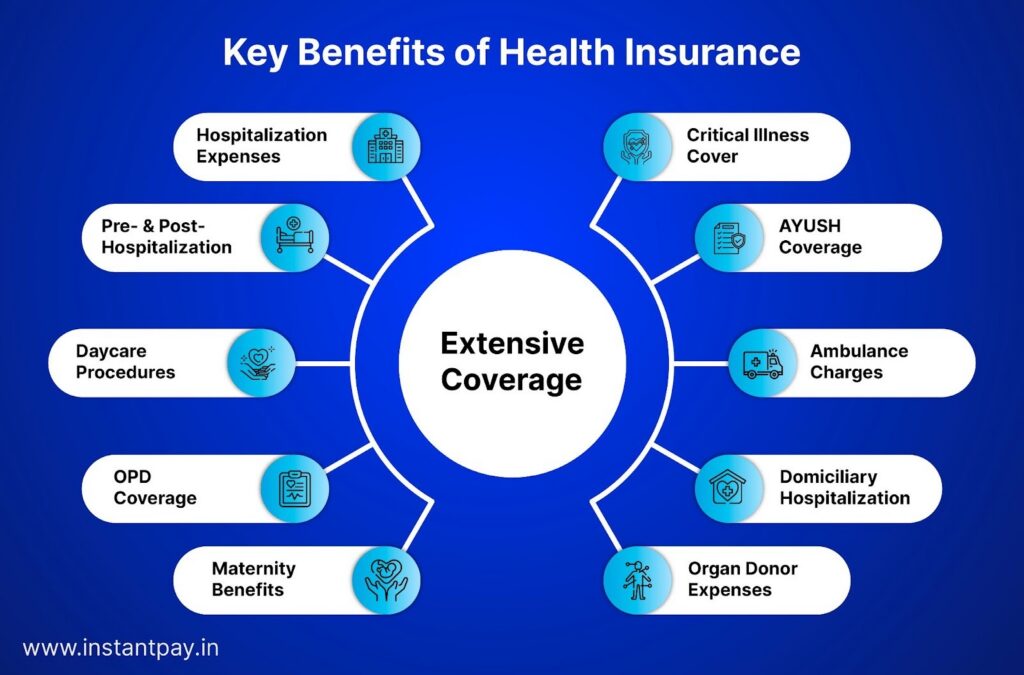
Healthhcare plan insurance can provide valuable financial protection through the payment of numerous expenses related to healthcare that occur prior to, during, or after treatment. These plans will provide you with funds to pay for unplanned healthcare programs.
Major benefits typically include:
1. Hospital Coverage—This type of policy will typically pay for your room (or ICU) costs, physician billing, surgical expenses, diagnostic testing, and other expenses associated with your hospital stay.
2. Pre- & Post-Hospitalization—This refers to medical expenses related to outpatient testing, medications, and follow-up physician visits.
3. Outpatient Treatment—Certain outpatient treatments do not require you to remain in the hospital for a 24-hour period. It will provide coverage for samples of outpatient treatment, including cataract surgery, dialysis, etc.
4. Critical Illness Insurance- Some insurance companies provide a once-a-year lump sum benefit if you should become critically ill (for example, with cancer, stroke, heart disease, etc.).
5. Maternity & Newborns- Some selected policies will cover pregnancy and newborn-related medical expenses for the policyholder after a waiting period and can apply to the baby also.
6. Available Limit—These insurance policies will generally provide a wide range of coverage limits, generally from Rs.500 to Rs.1,000,000.
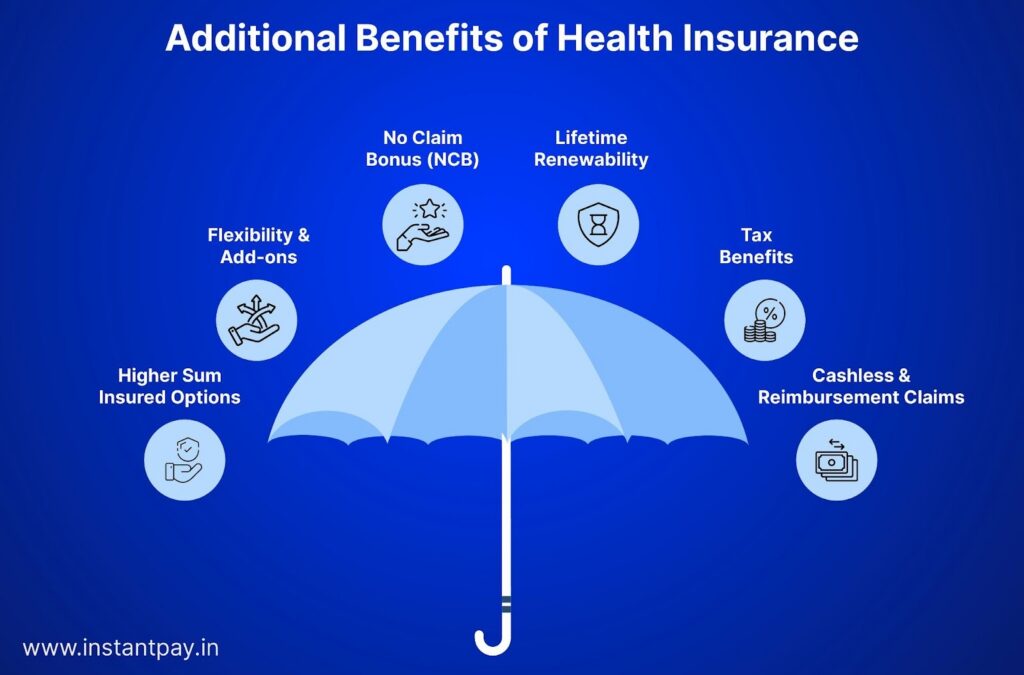
7. Cashless Treatment & Tax Benefits- Many medical coverage group systems will directly provide you cashless treatment while you are in a network hospital. In addition, you can deduct premiums up to a maximum of Rs.80,000 per year on your federal tax return using IRS Section 80D.
Mediclaim vs. Health Insurance: A Clear Comparison
| Feature | Mediclaim | Health Insurance |
| Scope of Coverage | Covers only hospitalization due to illness or accident. | Offers broader protection: hospitalization, daycare, critical illness, OPD (in some plans), maternity, and more. |
| Pre & Post-Hospitalization | Usually not covered. | Typically covered for 30–90 days before and 60–180 days after hospitalization. |
| Daycare Procedures | Not typically covered. | Covered, includes surgeries not requiring 24-hour admission. |
| Critical Illness Cover | Generally not included. | Often included or available as an add-on rider. |
| OPD Expenses | Not covered. | May be covered in comprehensive plans. |
| Maternity Benefits | Rarely covered. | Commonly covered after a waiting period. |
| Sum Insured | Lower, typically up to Rs.5 lakh. | Higher, ranging from Rs.50,000 to Rs.1 crore or more. |
| Add-ons / Riders | Very limited options. | Multiple riders available (e.g., accident, international cover). |
| Flexibility | Standardized coverage. | Highly customizable with add-ons and top-ups. |
| Premium | Lower premiums due to limited benefits. | Higher premiums, but broader and more valuable coverage. |
| Claim Settlement | Mostly reimbursement; some cashless options available. | Widely supports cashless and reimbursement claims. |
| Hospitalization Mandatory? | Yes, claim requires 24-hour hospitalization. | Not always, OPD or critical illness may not need hospitalization. |
How do you choose between Mediclaim and health insurance based on your needs?
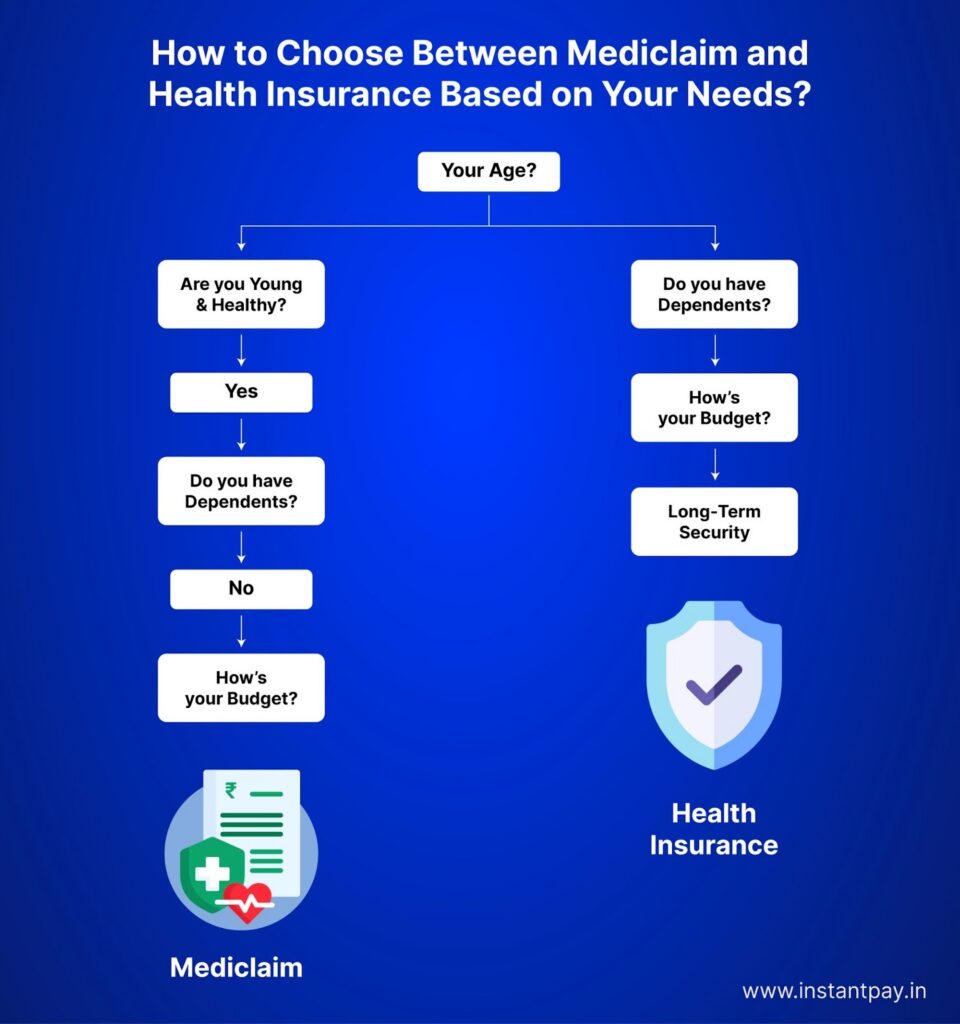
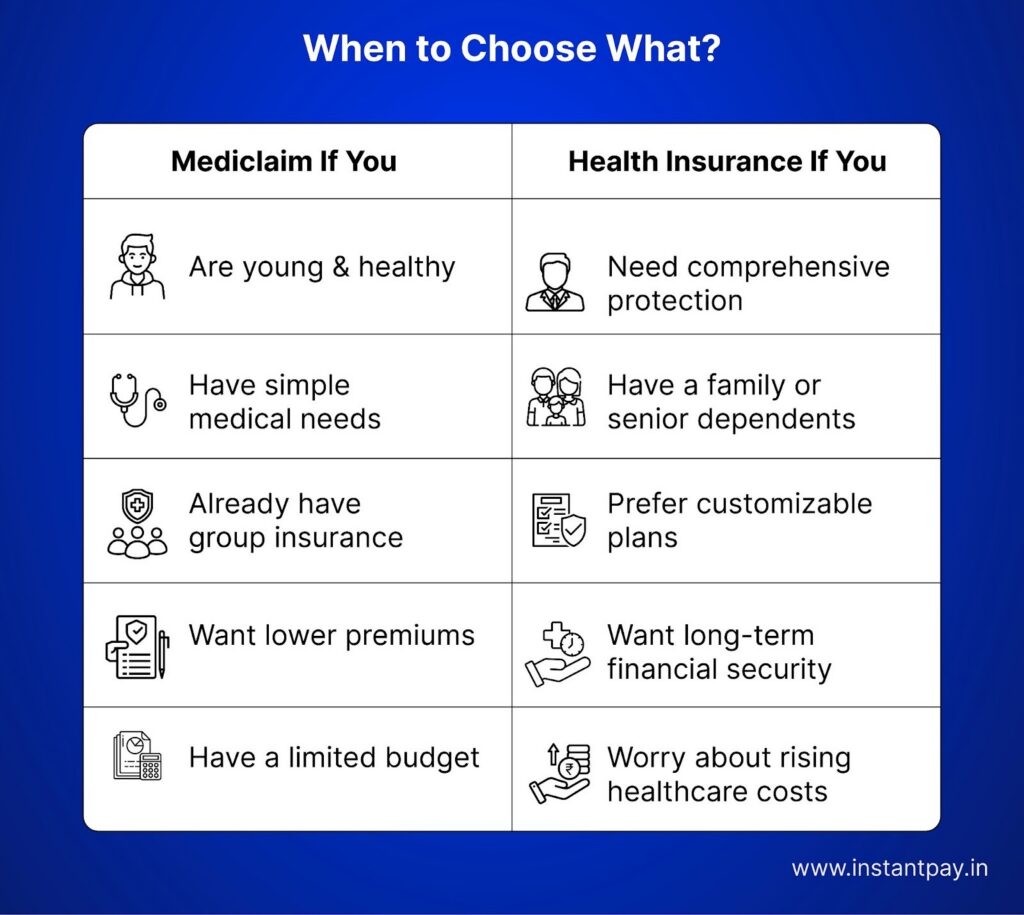
The age, need(s), and financial goals of you and your family will determine whether to choose Pre and post hospitalization expenses or health cover.
Opt for Cashless hopitalization if:
- You are young and healthy, with few healthcare needs.
- You need basic hospital coverage at lower rates.
- You have employer-supplied health cover and would like additional coverage.
Is Mediclaim good for senior citizens?
Not ideal. Health cover plan offers better coverage, especially for age-related or chronic illnesses.
Opt for healthcare plan if:
- You are 45 years or older, have pre-existing conditions, or want broader protection.
- You need to cover family members, including children and aging parents.
- You would like comprehensive benefits, such as critical illness, maternity, higher amounts of coverage, and long-term protection.
Which policy is right for my family?
Health cover policy offers better family-wide coverage with add-ons for maternity, daycare, and more.
What are the cost differences in Mediclaim vs. health insurance?
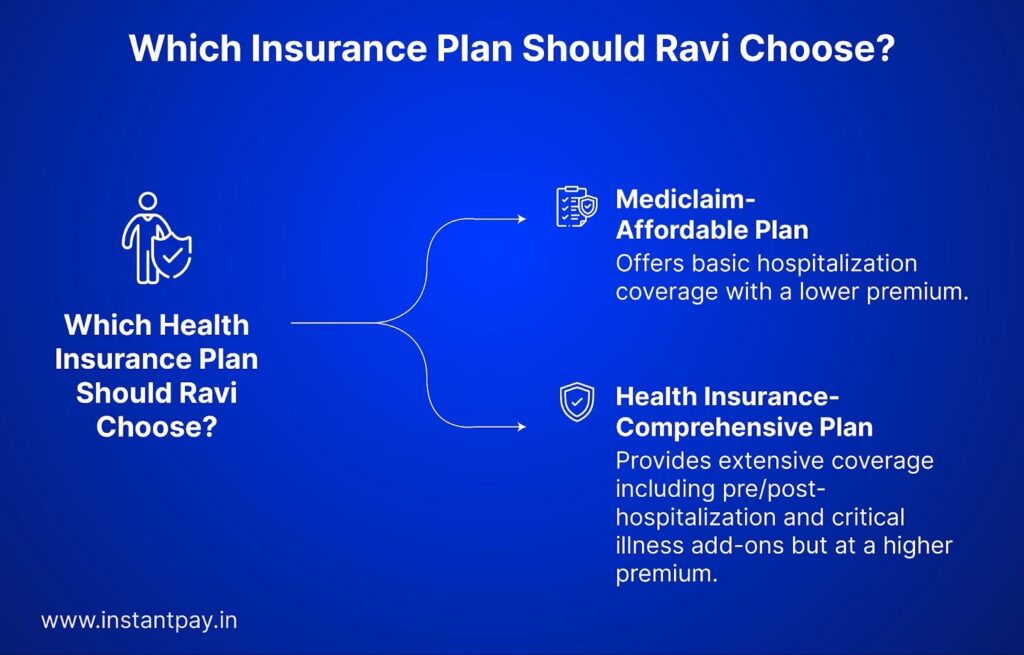
Scenario 1: A 27-Year-Old Freelancer
Profile:
Ravi, a 27-year-old freelance graphic designer, is healthy and rarely visits hospitals. He wants a low-cost plan to cover emergencies.
| Mediclaim Plan | Health Insurance Plan | |
| Annual Premium | Rs.3,000 | Rs.7,000 |
| Sum Insured | Rs.3 lakh | Rs.5 lakh |
| Coverage | Only hospitalization | Hospitalization, pre-/post-hospitalization, day care, critical illness add-ons |
| Outcome | More affordable, limited coverage | Wider protection Higher cost |
Best fit: Ravi opts for Cashless hopitalization for budget protection, planning to upgrade later as income grows.
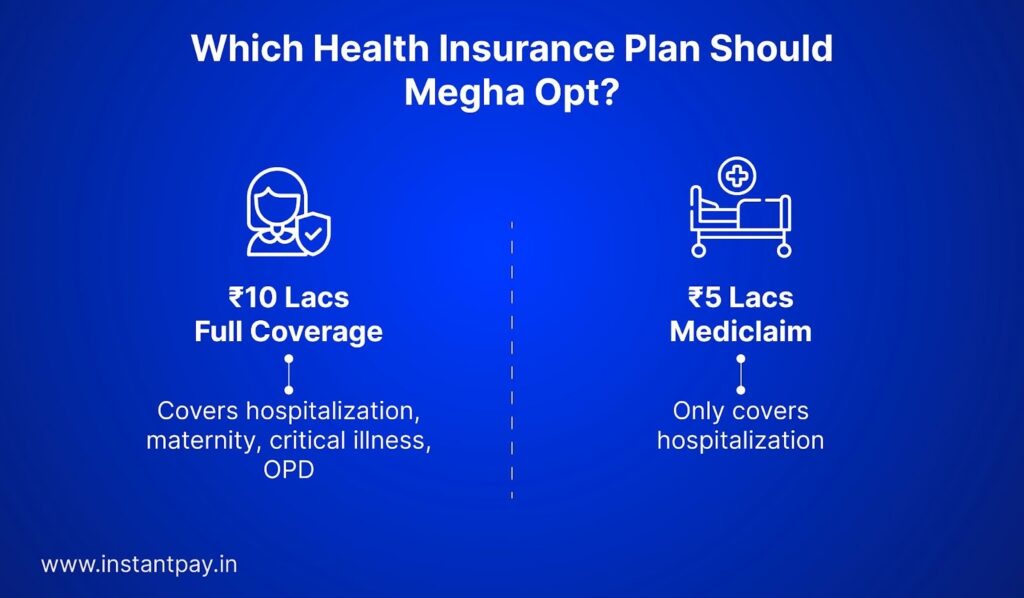
Scenario 2: A 35-Year-Old with a Young Family
Profile:
Megha, 35, has two children and a working spouse. She’s planning for maternity and OPD expenses for the kids.
| Mediclaim Family Floater | Health Insurance Floater Plan | |
| Annual Premium | Rs.8,000 | Rs.18,000 |
| Sum Insured | Rs.5 lakh shared | Rs.10 lakh shared |
| Coverage | Hospitalization only | Hospitalization, maternity, critical illness, OPD |
| Outcome | Lower premiumNo maternity or OPD | Full family coverageHigher cost |
Best fit: Megha selects a comprehensive health plan to secure her growing family’s needs.
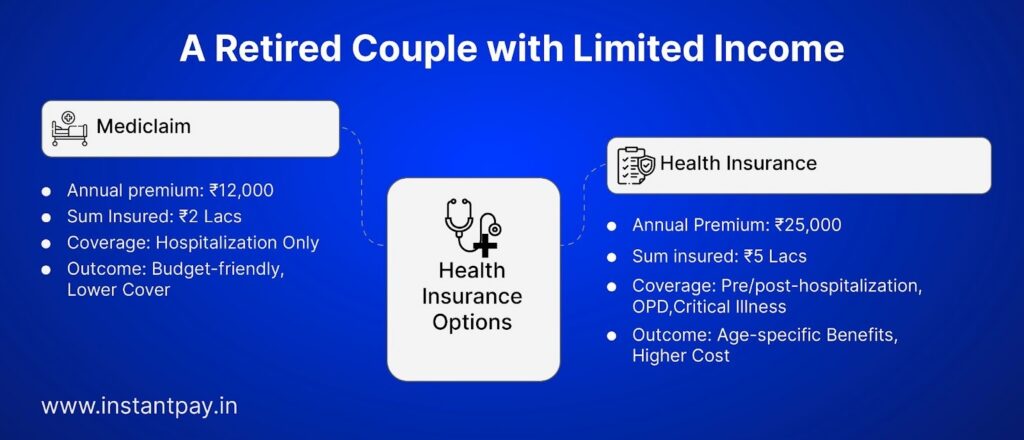
Scenario 3: A Retired Couple with Limited Income
Profile:
Ramesh and Sushma, a 62-year-old retired couple, are managing their health on a fixed pension.
| Senior Mediclaim | Senior Citizen Health Insurance | |
| Annual Premium | Rs.12,000 | Rs.25,000 |
| Sum Insured | Rs.2 lakh | Rs.5 lakh |
| Coverage | Hospitalization only | Pre/post-hospitalization, OPD, critical illness |
| Outcome | Budget-friendlyLower cover | Age-specific benefitsHigher cost |
Best fit: They choose the health plan despite higher cost, valuing wider coverage and peace of mind.
Key Takeaway
While Cashless hopitalization plans offer low-cost protection for basic needs, comprehensive healthcare plan is better suited for families, older individuals, and those anticipating higher medical expenses. Your age, family size, health condition, and budget should guide your decision.
Tip: Use a health policy premium calculator to compare plans tailored to your age, lifestyle, and risk preferences.
What are the advantages and disadvantages of health insurance?
When compared to standard cashless hospitalization, a health cover plan provides significantly broader coverage for all of your different healthcare costs. While health cover has many benefits, there are also some trade-offs that come with it.
Benefits of Health Cover Plan
- Comprehensive Coverage: Coverage includes everything from hospitalization to pre- and post-hospitalization, daycare procedures, and critical illnesses. Some health plans also include maternity and OPD treatment.
- Higher Sum Insured: Health coverage plans normally have a sum insured value of anywhere between Rs.5 lakh and Rs.1 crore to help cover large medical bills.
- Customized Plans: Medical insurance offers optional add-ons that give you the choice of increasing your coverage based on your specific needs.
- Cashless Treatment: Many networked hospitals provide cashless treatment, making it easy to settle any claims made from using medical insurance.
- Tax Benefits: The premium for the health plan you buy qualifies as a deduction under Section 80D of the Income Tax Act.
Drawbacks of Health Cover Plan
- Higher Premiums: Because the coverage is so much larger on a healthcare policy, these plans typically charge a higher premium than other types of insurance coverage.
- Longer Waiting Periods: If you have a pre-existing condition, you will not be able to claim it under a medical insurance policy for at least 2 to 4 years after taking it out.
- Increasing Premiums: The average premium for health cover generally goes up as you age.
What are the benefits and drawbacks of Mediclaim?
Mediclaim provides basic financial protection against hospital costs not offered by comprehensive health cover.
Advantages of mediclaim
- Low premiums: Affordable Cashless hopitalization policies can be purchased at a relatively low cost (i.e., Rs.2,000 to Rs.3,000 per annum) for individuals or households on limited budgets.
- Simple Coverage: Primarily focuses on hospital expenses only; therefore, the policy is straightforward to understand.
- It can be utilized as an additional source of security because many of these policies are available even if your employer provides health policy.
Disadvantages of mediclaim
- Limited coverage: Cashless hopitalization does not typically provide coverage for outpatient services, maternity care, daycare surgery, and critical illness.
- Lower sum insured: The sum insured is limited (typically between Rs.2,00,000 and Rs.5,00,000), which is not likely to be sufficient to cover the costs of a major illness.
- Limited options: Sum assured plans typically do not provide much flexibility in terms of add-ons or options to increase the level of coverage.
Is Mediclaim the Same as Health Insurance? Common Myths Explained
| Myth | Fact |
| Mediclaim = Health Insurance | Mediclaim only covers hospitalization. Health insurance includes wider benefits: pre/post-hospital care, OPD, add-ons. |
| OPD is always covered | Most basic plans (esp. Cashless hopitalization) exclude OPD unless added specifically in health insurance. |
| Mediclaim is outdated | It still works for low-budget, hospitalization-only needs, especially for young or healthy individuals. |
| 24-hour hospitalization is mandatory | Not many health insurance plans cover daycare treatments like cataract or chemotherapy. |
| Insurance covers all costs from day one | Waiting periods apply for pre-existing illnesses, maternity, etc., usually 1–4 years. |
| Missed renewal = all benefits lost | Most insurers offer a 15–30 day grace period to renew without losing continuity. |
| I don’t need insurance if I’m healthy | Accidents and medical emergencies are unpredictable. Insurance offers financial security, not just illness protection. |
| All policies are the same | Features, exclusions, and benefits vary. Always compare beyond just premiums. |
| Pre-existing diseases are never covered | They are covered, but only after a waiting period, based on your policy terms. |
Key Decision Factors to Consider Before Buying Mediclaim or Health Insurance
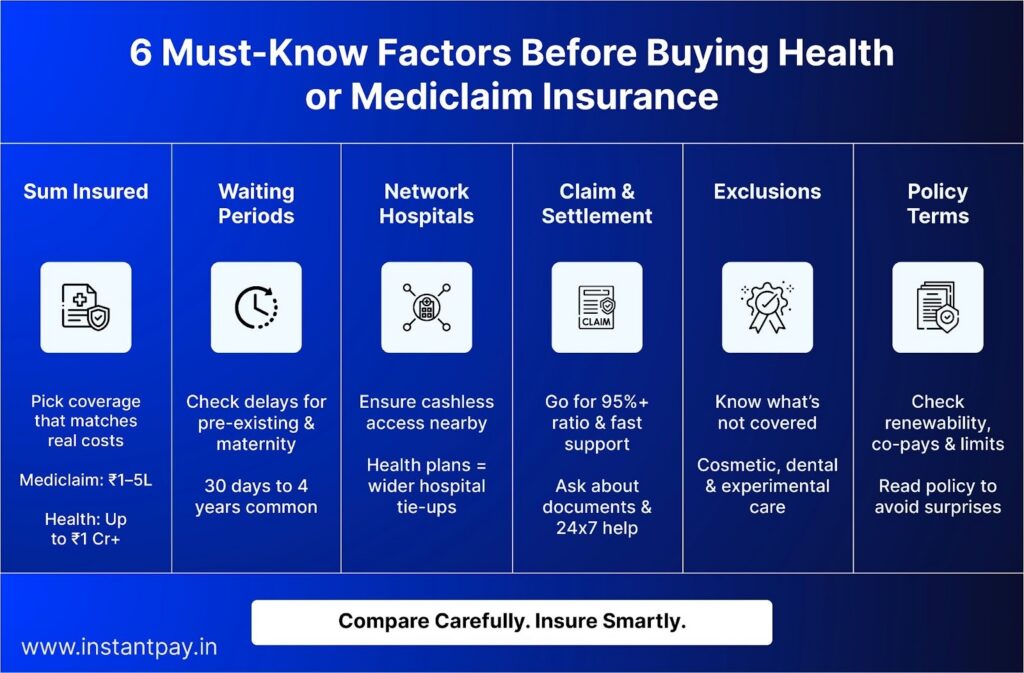
Whether you’re considering Cashless hopitalization or a comprehensive health insurance policy,here are the essential factors to review before making a decision.
1. Sum Insured: Think Beyond the Basics
The sum insured is the maximum amount your insurer will pay during a claim.
- Cashless hopitalization policies usually offer lower coverage (Rs.1–5 lakh), suitable for basic hospitalization needs.
- Health cover policy provides a broader range (Rs.5 lakh to Rs.1 crore+), ideal for rising healthcare costs and advanced treatments.
Tip: Always assess your family size, city of residence, and current healthcare inflation while choosing your coverage.
2. Waiting Periods: Know When the Clock Starts
Most policies come with waiting periods before certain benefits kick in.
- Common delays include 30 days for new policies, 2-4 years for pre-existing diseases, and 9 months for maternity.
- Mediclaim and health insurance both have these, but the scope of waiting period coverage varies.
“What is the waiting period for mediclaim?”
Most Cashless hopitalization plans have a 30-day general waiting period and up to 4 years for pre-existing conditions.
3. Network Hospitals: Check for Local Access
A strong network of empanelled hospitals ensures you can use cashless claims in emergencies.
- Cashless hopitalization plans may have a smaller or more restricted list.
- Health insurance providers often tie up with a wider range of hospitals, including multi-specialty centers and urban chains.
Always confirm if your preferred hospitals are on the list before purchase.
“How does cashless mediclaim work?”
If treated at a network hospital, the insurer pays directly, and you avoid out-of-pocket payments (except non-covered items).
4. Claim Process & Settlement Ratio: Speed Matters
It’s not enough to be insured; your claim must be processed quickly and fairly.
- Look for insurers with high claim settlement ratios (above 95%) and 24×7 support.
Ask about the documentation process for both cashless and reimbursement claims.
“How do I claim mediclaim insurance?”
Submit the hospital bills and treatment documents within the insurer’s deadline. For cashless, pre-authorisation is needed.
5. Exclusions & Hidden Clauses: Read the Fine Print
Both Cashless hopitalization and health policies come with standard exclusions like:
- Cosmetic surgeries
- Dental treatments (unless accidental)
- Experimental procedures
- Pre-existing illnesses (during waiting periods)
Always review the exclusions section and ask your insurer to clarify coverage gaps before signing.
6. Policy Terms & Renewability: Plan for the Long Run
- Choose plans with lifelong renewability, so you’re protected well into old age.
- Check age limits, co-pay clauses, and sub-limits on room rent or ICU charges. These often make a big difference during actual claims.
Choosing the right plan isn’t just about premium or coverage. It’s crucial to read the policy document thoroughly to understand co-pay clauses, exclusions, and limits. Our blog on How to Read a Health Insurance Policy simplifies this process and helps you spot the fine print that matters.
Tax Benefits of Mediclaim and Health Insurance in India: What You Can Claim Under Section 80D
Both Cashless hopitalization and health cover policies are eligible for tax deductions under Section 80D of the Income Tax Act. These benefits make them not just a health safeguard, but also a smart financial move.
How Much Tax Can You Save?
| Policyholder | Deduction Limit (Old Regime) |
| Self, Spouse & Children (below 60) | Up to Rs.25,000 |
| Parents (below 60) | Additional Rs.25,000 |
| Parents (above 60) | Additional Rs.50,000 |
| Self & Parents (both above 60) | Up to Rs.1,00,000 total |
Note: These deductions apply only under the old tax regime. New regime taxpayers are not eligible for 80D deductions.
What Expenses Are Covered?
- Premiums paid for sum assured or health cover policies
- Preventive health check-ups (up to Rs.5,000 included within the limit)
- Top-up or super top-up health coverage premiums
Final Thoughts
The difference between health insurance and mediclaim lies in their scope, flexibility, and suitability based on individual needs. Whether you’re buying your first policy or looking to upgrade your coverage, it’s important to align your choice with your life stage, financial comfort, and healthcare expectations.
If you’re young, healthy, and primarily concerned about emergency hospitalization, a sum assured medical cover policy might be an affordable way to get started. But as responsibilities grow, whether it’s supporting a family, managing chronic health conditions, or preparing for maternity or senior care, health policy becomes a more practical and comprehensive option.
Your decision should also reflect your budget and long-term risk tolerance. Mediclaim plans offer basic protection at lower premiums, while modern health cover plans provide wider coverage, including OPD, diagnostics, mental health, and critical illness riders. Understanding these differences is key to making an informed, future-proof choice.
FAQs
1. What is the main difference between Pre and post hospitalization expenses and health insurance?
Pre and post hospitalization expenses only cover hospital expenses. Health covers more, like hospital bills, doctor visits, tests, and sometimes critical illnesses.
2. Is mediclaim and health cover policy the same thing?
No, they are not the same. Pre and post hospitalization expenses are a basic type of coverage, while health insurance gives wider protection.
3. Which is better: mediclaim or health plan?
It depends on your needs. Pre and post hospitalization expenses are good for low cost and basic cover. Health insurance is better if you want full protection for you and your family.
4. Do pre- and post-hospitalisation expenses cover doctor visits and medicines?
Usually no. Cashless hospitalization mostly covers only hospital stays, not regular doctor visits or medicines.
5. Can I have both mediclaim and health policy?
Yes, you can have both. Some people use cashless hospitalization as extra coverage along with a health insurance plan.