The poverty rate in India increased from 16.44% to 19.05% when accounting for out-of-pocket (OOP) expenses associated with healthcare, resulting in approximately 6.47 million families becoming impoverished. Though families have a range of available health plan options, many still incur debt because they fail to enroll in or renew their health insurance policy on time, which can lead to a lapse in coverage and being uninsured for necessary healthcare.
For many individuals, the primary consideration of medical coverage policyholders is the premium, the hospitals on the insurance company’s list of hospitals that provide services, and the total amount of the benefit offered, rather than focusing on the fine print of the policy that identifies when they can purchase, change, or activate their insurance coverage.
This blog post provides an overview of the various types of open enrollment, special enrollment events, and deadlines for medical insurance policies so that there is no possibility of being covered only on paper.
What Are Enrollment Periods in Health Insurance?

Enrollment periods are defined intervals when you may buy, renew, or change your health insurance plan. Insurers and regulators establish these times to keep the marketplace fair for everyone. Missing a sign-up period may delay your ability to obtain coverage and, in some cases, may result in claim denials.
Here’s Why It’s Important.
Enrollment periods are the determining factor when your financial protection starts. If you miss them, you may stay uninsured until the next coverage enrollment window opens. If you miss your health insurance enrollment window, you will likely be responsible for most of the bill, considering that the average cost of one hospitalization in a private hospital is approximately Rs.32,000 nationally and nearly Rs.39,000 in urban areas.
Who Sets These Dates?
Coverage enrollment window are defined according to the type of policy you have:
- Retail health policies: Insurers determine the enrollment periods, which are regulated by IRDAI.
- Employer Group Coverage: Typically follows the annual renewal cycle established by your employer’s policy.
- Government-sponsored programs: Many do allow open enrollment throughout the year but may require alternative documentation to enroll.
Open Enrollment Period: The Main Window
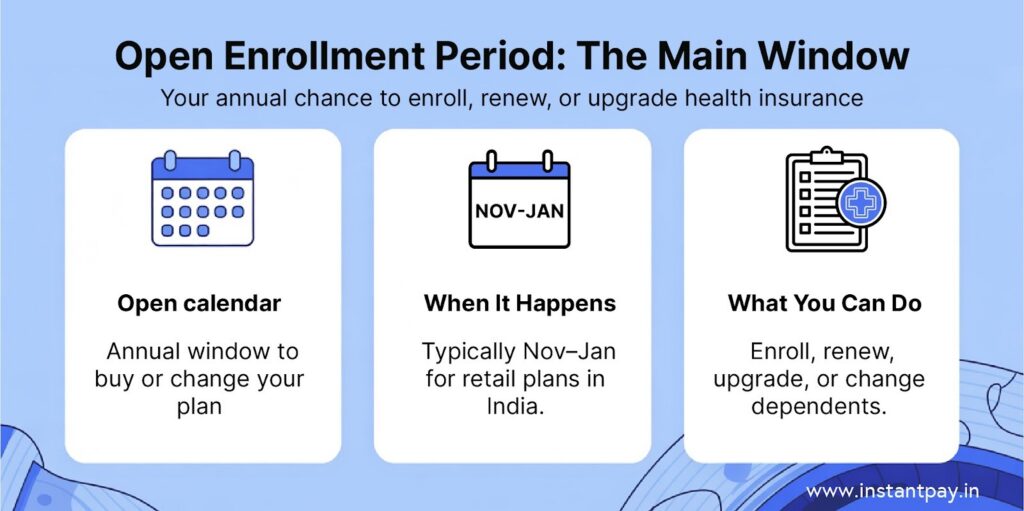
The Open Enrollment is a major opportunity for you to acquire or change a medical insurance policy. Should you miss this open enrollment, generally, you must wait until the following open enrollment unless you are eligible to apply for or receive a special enrollment window.
When It Happens Each Year:
- For the majority of Indian retail health insurers, the open enrollment period normally runs between the months of November and January each year. In comparison, the dates of the open enrollment for government- and employer-sponsored insurance will differ due to their policy cycles and so on.
What You May Do in Open Enrollment
- During the health insurance open enrollment, you may:
- Purchase New Individual or Family Health Insurance Plan
- Renew Existing
- Raise/Upgrade Sum Insured
- Add/Remove Dependents From the Coverage of Your Policy
Enroll in a New Plan
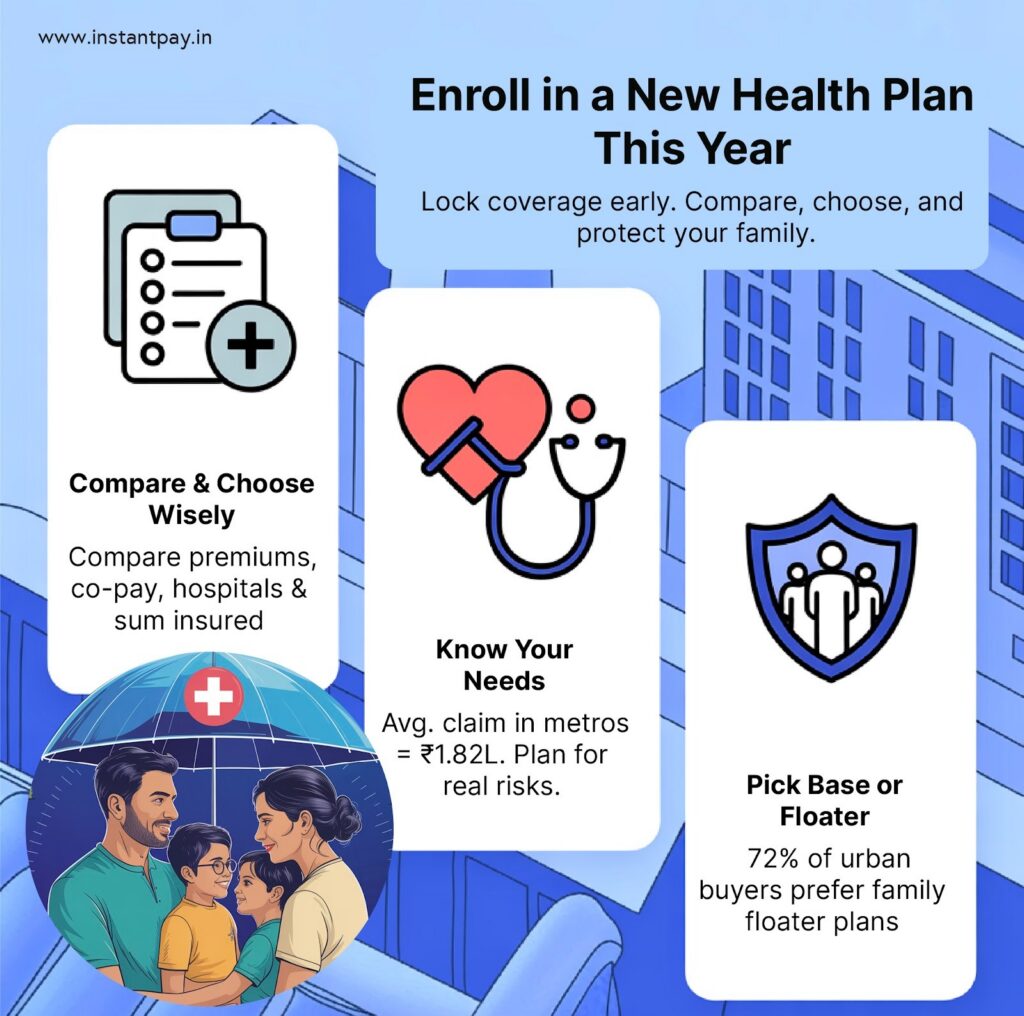
If you are a first-time medical insurance buyer, then opting for the Open Enrollment could be a good choice. Each year medical prices will go up, so enrolling early allows you to lock in your insurance coverage before the premiums increase. You can utilize this time to compare health plans, look at the networks of hospitals at which you can receive treatment or care, and decide whether you want to purchase for just an individual or for a family (family floater).
What Can You Do?
Compare and evaluate your coverage options. The IRDAI licenses more than 30 insurance companies in India to issue individual and family health policies. Compare all premiums, networks of hospitals, co-pay clauses, and the sum insured using either Policybazaar or the IRDAI consumer portal.
Assess your health care needs. Lifestyle diseases like diabetes and hypertension have caused more people to visit hospitals than when they were younger (during their 30s).
Why Does It Matter?
Buying health coverage early helps you start waiting periods sooner, which are usually 2–4 years for pre-existing diseases, maternity benefits, and certain treatments. Early enrollment also helps keep premiums lower over time.
Renew or Upgrade Coverage
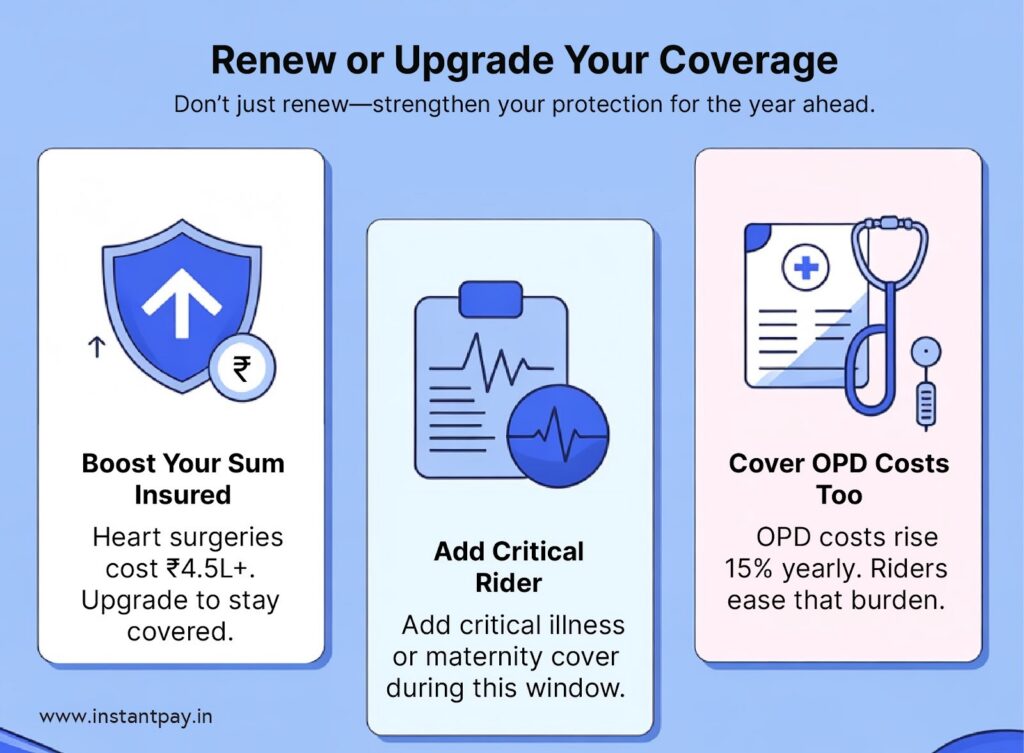
The open enrollment period is also the right time to improve your protection and add coverage for medical needs that may arise later. You can increase the sum insured during this period, as well as include riders to enhance your level of protection.
For instance, heart bypass surgery can cost between Rs.350,000 and Rs.450,000 in Tier-1 cities (Apollo Hospitals, 2024), so a cover of Rs.300,000 may not give you adequate coverage.
What You Can Do:
- Increase your sum insured: You may require more than just Rs.300,000 for major medical procedures; health experts will recommend a minimum cover of Rs.1,000,000 – Rs.1,500,000, especially if you live in an urban area with a family.
- Add riders that can help you cover most of your healthcare costs.
- Critical Illness Rider: This covers the major diseases and pays a lump sum. There were over 1.5 million new cancer cases reported in India annually (ICMR, 2023).
- Maternity: Delivering in a private hospital may cost between Rs.60,000 and Rs. 120,000.
- Outpatient Rider: This will cover the outpatient expenses such as doctor visits and laboratory services, as outpatient expenses continue to rise every year.
Why It Matters:
Insurers allow mid-year upgrades only if you switch plans. Missing this chance could leave you underinsured for the next 12 months.
Add or Remove Dependents
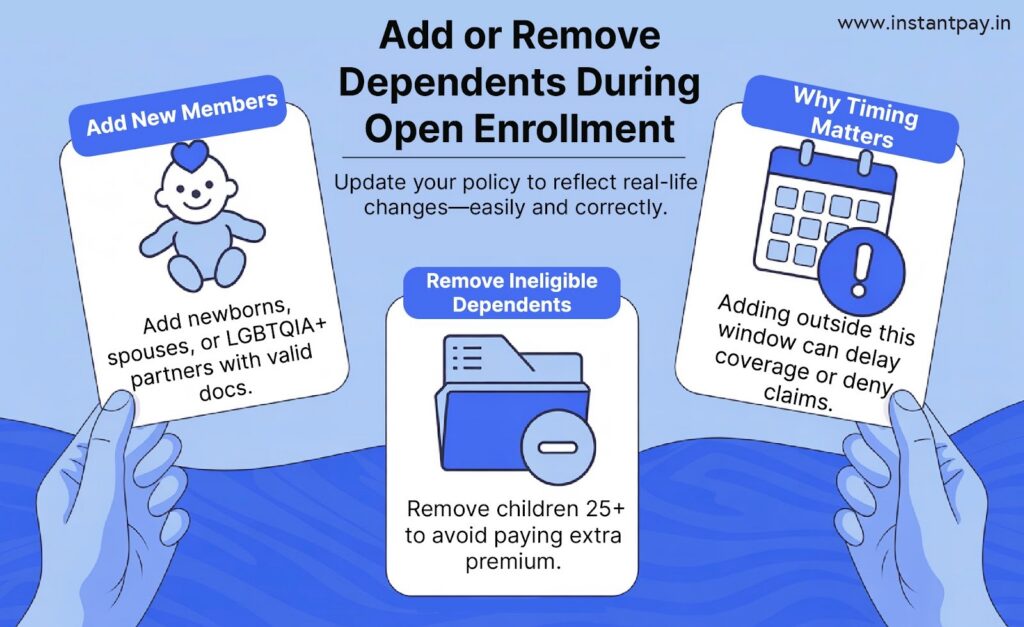
Your family situation is constantly changing, and so should your health cover policy. You can add your spouse/a new dependent during the open enrollment period. You can also remove others from your plan who no longer qualify. This keeps your family’s health coverage current and eliminates the chance for you to pay more than necessary.
What You Can Do:
- To add a dependent:
• Most Family Floater plans will allow you to include new babies in their coverage within 90 days of birth.
• Most plans will allow you to include your spouse up to 30-60 days after you get married, provided you have the necessary documents.
• Most plans allow you to include your same-sex (LGBTQIA+) partner under the updated IRDAI guidelines.
- To remove a dependent:
• If your children turn 25, they generally will be required to have their own individual policy.
Why It Matters:
Updating your dependents in a timely manner is critical to preventing issues with claims, waiting periods, or delays in coverage.
What Happens If You Miss the Open Enrollment Period?
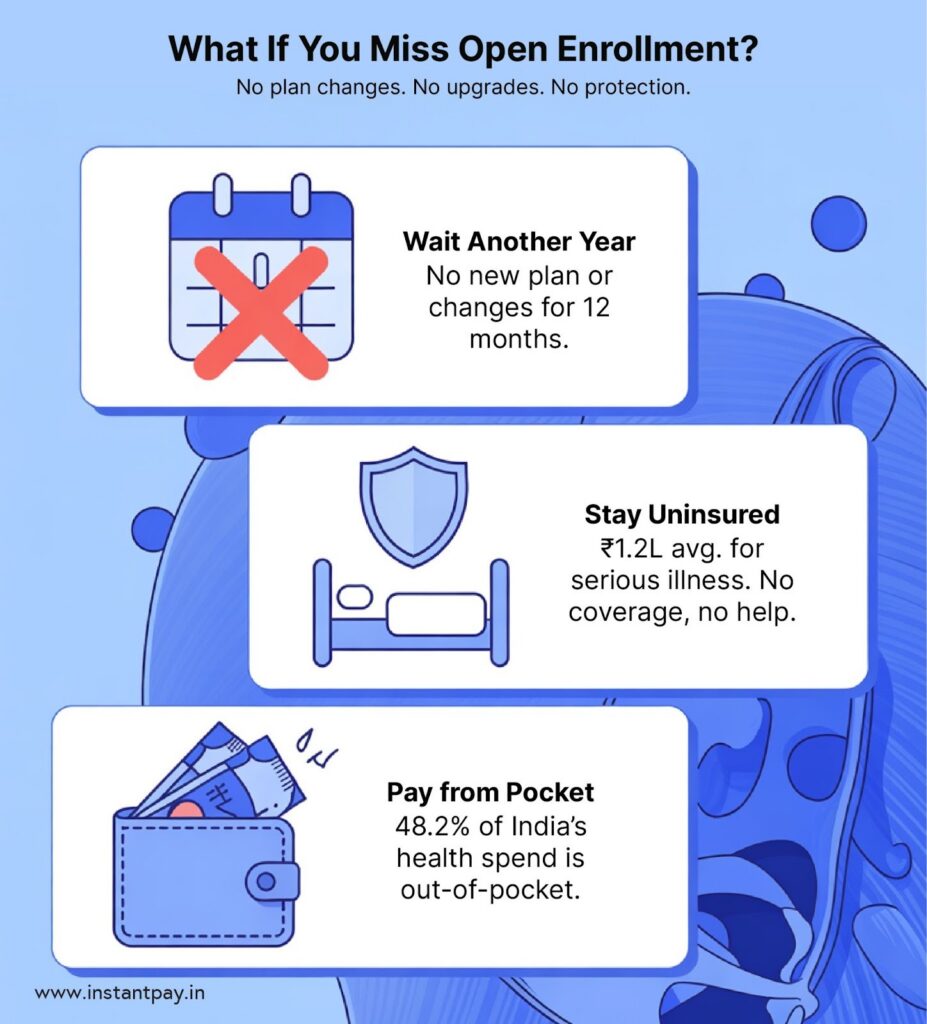
Many people believe they can purchase insurance at any time they wish; however, that is not the case. If you miss out on the annual open enrollment period and do not qualify for a special enrollment period due to a qualifying life event (marriage, birth of a baby, loss of job, or relocation), you may experience gaps in coverage.
1. You May Need to Wait Until the Next Enrollment Period
If you miss the open enrollment deadline, you typically will not be allowed to purchase or upgrade your insurance coverage until the next enrollment period, which could range from six to twelve months away. If you have not renewed your insurance policy at the end of your current plan year, you must keep your existing plan for the duration of the current plan year and continue paying for it.
2. You Could Remain Uninsured
Missing open enrollment and having no insurance may leave you uninsured for an entire year, leaving you at risk of incurring high medical costs.
3. You Will Pay Your Own Medical Expenses
If you don’t have insurance, you’ll have to pay for medical care out of pocket. As a result, you will not have:
- No cashless hospitalization
- No reimbursement for your medical treatment
- No benefits for diagnostics, or pre/post hospitalization treatments
- No tax benefits for anything under Section 80D
Action vs Consequence if You Miss the Open Enrollment Window
| Action You Intended to Take | What Happens If You Miss It |
| Enroll in a new health insurance plan | You remain uninsured for the year unless you qualify for a Special Enrollment Period. |
| Increase your sum insured | You’re locked into lower coverage for 12 more months—leaving you underinsured in crises. |
| Add a spouse, newborn, or dependent | You can’t add them until the next cycle; any medical expenses will not be covered. |
| Remove a non-dependent (e.g., adult child) | You continue paying a premium unnecessarily for someone who’s no longer eligible. |
| Add critical illness or maternity rider | You miss out on enhanced protection during emergencies or planned medical events. |
| Shift to a better insurer (portability) | You must wait another year to port your plan—delaying access to better benefits. |
| Renew an expiring policy | If lapsed, you may lose No Claim Bonus and all waiting period benefits. |
| Recalculate needs based on health history | You stay in a misaligned policy, paying more for less protection or facing denial risks. |
Special Enrollment: Life Events That Qualify

Not everyone’s life fits into a rigid calendar. That’s why special enrollment periods (SEPs) exist. These allow you to enroll or make changes to your policy outside of open enrollment if you experience a qualifying life event.
Marriage, Divorce, or Childbirth
Adding a new family member or losing a dependent changes your health needs—and qualifies you for SEP. Most insurers allow a 30-day window from the event to update your plan.
Job Loss or Income Change
Losing group insurance due to job loss or transitioning to freelancing also qualifies you. This is especially critical as you’re no longer protected under your employer’s umbrella.
Moving to a New Location
If you move cities or states, you may need a new plan to align with local network hospitals. Insurers consider this a valid SEP (Special Enrollment Period) trigger.
Loss of Employer Coverage
If your corporate policy ends for any reason, you can shift to an individual retail plan without losing continuity benefits.
What is the enrollment period duration?
Insurers generally allow a 30–60 day window post-event for enrollment. Timely action and proof of the qualifying event are essential to avoid rejection.
Enrollment Periods by Plan Type
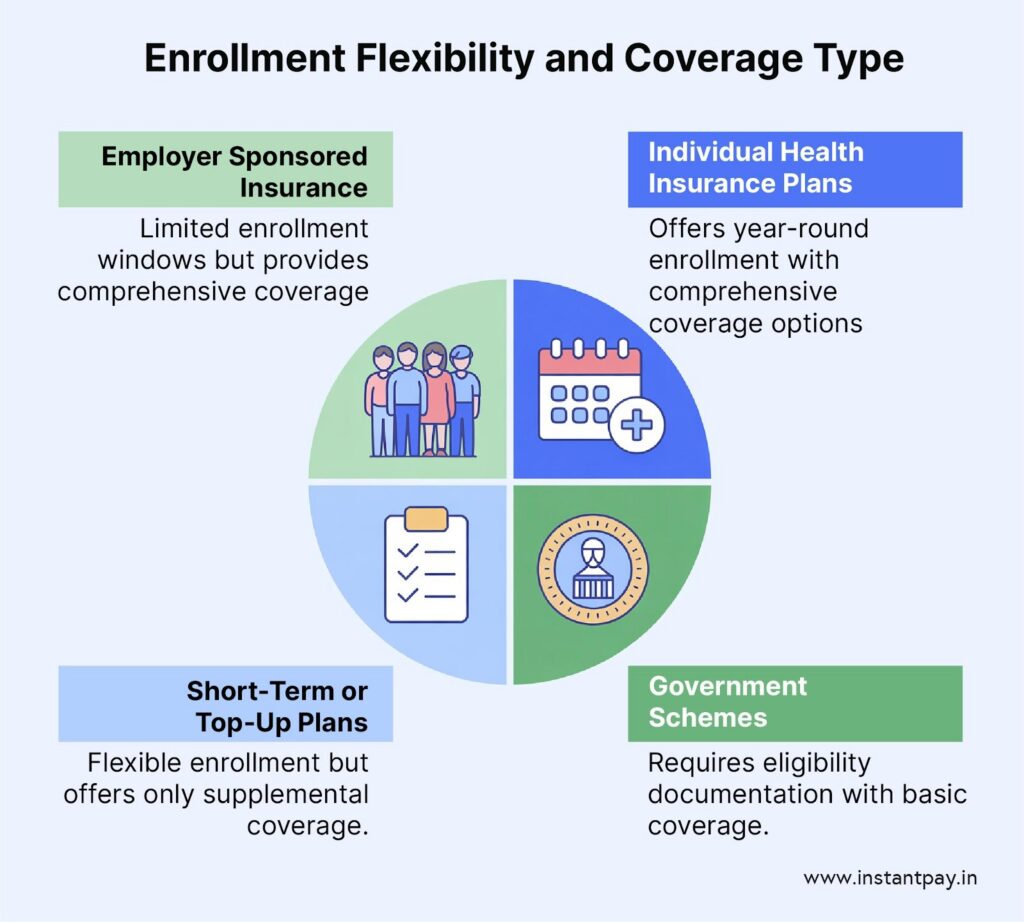
Enrollment flexibility varies by the type of healthcare coverage you have. Here’s a breakdown:
Individual Health Insurance Plans
These are sold by private insurers and can often be purchased year-round, but they may come with initial waiting periods. Renewing on time is crucial to avoid losing your No Claim Bonus (NCB) or having waiting periods reset.
Employer-Sponsored Insurance
Typically offered during onboarding or annual review cycles. Miss this window, and you may not be able to modify coverage until the next year, unless a qualifying life event occurs.
Government Schemes Like Ayushman Bharat
These are often available year-round but require eligibility documentation.
Stat: Over 55 crore Indians were enrolled under PM-JAY as of 2024 (National Health Authority).
Short-Term or Top-Up Plans
These plans often allow enrollment anytime but require a base policy for activation. They are designed for supplemental coverage and don’t replace full health insurance.
How to Prepare for Enrollment?

Smart preparation can help you make the most of your enrollment window:
Review Past Medical Expenses
Understand your hospitalization and outpatient costs over the past year to choose appropriate coverage.
Check Policy Documents and Renewal Dates
Ensure your current policy hasn’t lapsed. A missed renewal can erase accumulated bonuses and require re-initiating waiting periods.
Compare Plans and Premiums
Use platforms like Policybazaar or IRDAI’s portal to evaluate claim settlement ratios, exclusions, and network hospitals.
Gather Required Documentation
Keep your ID proofs, medical history, and income details ready. This simplifies the application and reduces approval delays.
Stay Smart: Use SMS/email alerts and work with a licensed advisor to never miss an enrollment deadline again.
Tips to Avoid Missing Deadlines

Set Calendar Alerts for Key Dates
Use your phone, Google Calendar, or any app to create multi-layered alerts (30 days, 7 days, and 1 day before expiry).
Sign Up for Email or SMS Reminders
Most insurers offer timely reminders. Make sure notifications are enabled in your user dashboard.
Work With a Certified Insurance Advisor
A trusted advisor can help track deadlines, compare plans, and even manage your claim documentation.
Final Thoughts: Stay Ready, Stay Covered
Let’s return to where we started. My colleague didn’t lack insurance; she lacked understanding. And it cost her dearly.
Enrollment periods for health insurance may seem bureaucratic, but they serve a vital purpose. Missing them can mean:
- Going uninsured
- Paying huge medical bills out of pocket
- Losing policy benefits you’ve built over time
In a healthcare landscape where a single hospitalization can cost Rs.5–7 lakh, timing is everything.
So ask yourself:
Are you prepared for the next enrollment window?
Do you know when your policy renews or how to switch if needed?
Because in the world of healthcare, what you don’t know can hurt you and your wallet.
Frequently asked questions (FAQ’s)
1. What is an open enrollment period in health insurance?
It’s a designated time frame during which individuals can enroll in, renew, or make changes to their health insurance plans without needing a qualifying life event.
2. When does the open enrollment period typically occur in India?
For most retail health insurance plans, it usually runs from November to January. However, employer-sponsored plans may have different dates.
3. Can I enroll in health insurance outside the open enrollment period?
Yes, but only if you experience a qualifying life event, such as marriage, childbirth, or job loss, which makes you eligible for a Special Enrollment Period.
4. What qualifies as a life event for special enrollment?
Events like marriage, divorce, birth or adoption of a child, loss of other health coverage, or moving to a new area can qualify you for special enrollment.
5. How long do I have to enroll after a qualifying life event?
Typically, you have 30 to 60 days from the date of the event to enroll in a new health plan or make changes to your existing one.
6. What happens if I miss the open enrollment period?
You may have to wait until the next open enrollment period to enroll or make changes, unless you qualify for a special enrollment period.
7. Can I change my health insurance plan during open enrollment?
Yes, open enrollment is the time to review your current plan and make changes, such as switching plans, adding or removing dependents, or adjusting coverage levels.
8. Are there any exceptions to the open enrollment period?
Yes, certain government schemes like Ayushman Bharat may allow enrollment year-round, subject to eligibility criteria.
9. How do I know if I’m eligible for a special enrollment period?
Eligibility depends on the occurrence of specific life events. It’s best to check with your insurance provider or HR department for guidance.
10. Is there a waiting period after enrolling in a new health insurance plan?
Most health plans have a waiting period, typically 30 days for general coverage and up to 2-4 years for pre-existing conditions.
11. Can I add dependents to my health insurance plan during open enrollment?
Yes, open enrollment is the appropriate time to add dependents like a spouse, children, or parents to your plan.
12. What documents are required to enroll in a health insurance plan?
Commonly required documents include identity proof, address proof, age proof, income proof, and medical reports, depending on the insurer’s requirements.
13. Can I cancel my health insurance plan during open enrollment?
Yes, you can choose to cancel or not renew your health plan during the open enrollment period.
14. Are premiums affected if I enroll during a special enrollment period?
Premiums are generally based on factors like age, coverage amount, and health status. Enrolling during a special enrollment period doesn’t typically affect the premium rates.
15. Where can I get assistance with the enrollment process?
You can seek assistance from insurance agents, brokers, or directly from insurance companies. Many insurers also offer online enrollment support.